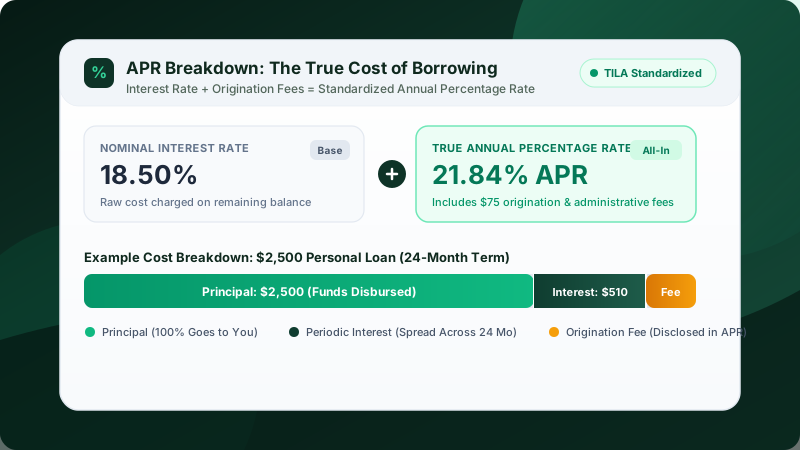
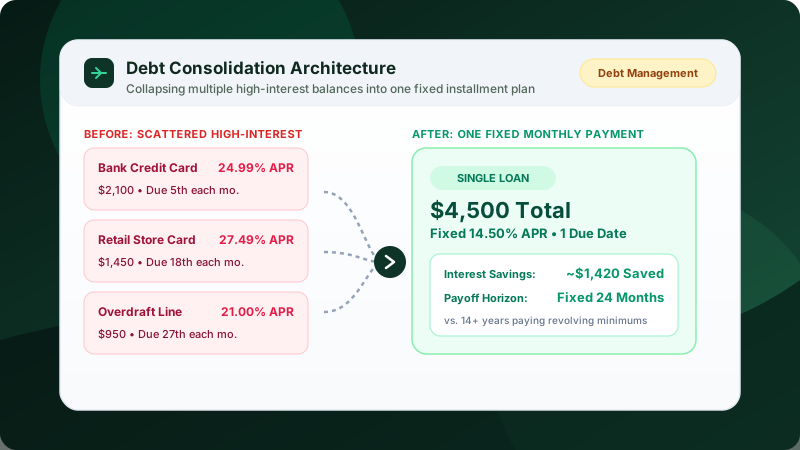
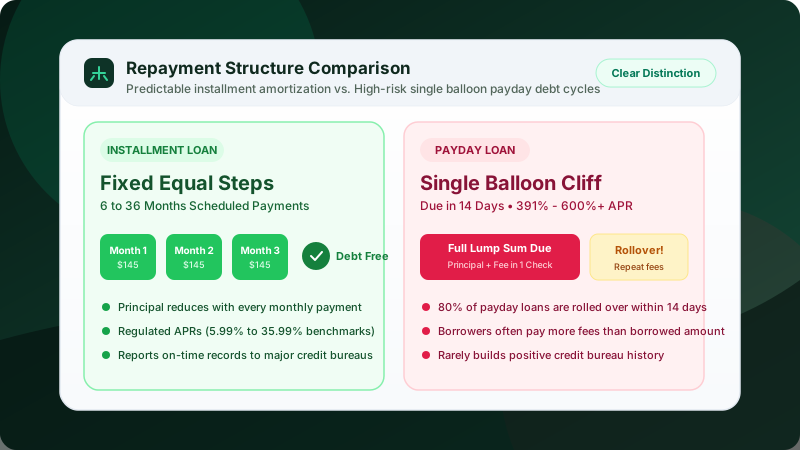
One of the most frequent consumer questions when considering an installment loan is: "Will exploring options damage my credit score?" The answer depends on where you are in the application journey.
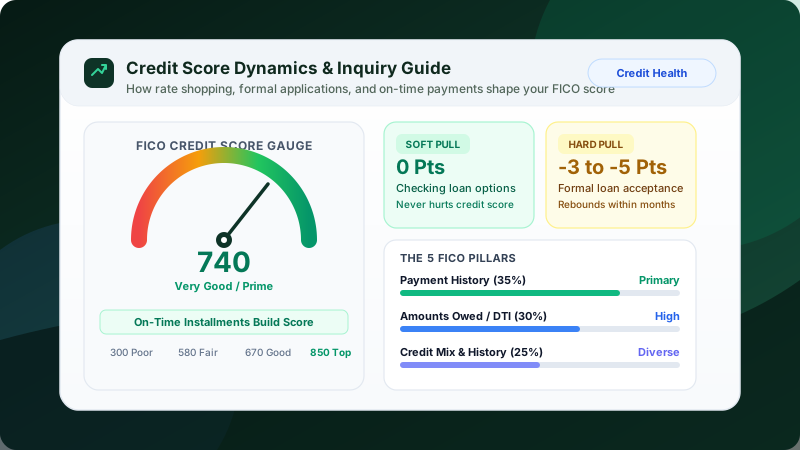
1. Soft vs. Hard Credit Pulls: What Happens When You Inquire?
There are two distinct types of credit inquiries recognized by credit bureaus:
- Soft Credit Inquiry: Used for pre-qualification, background checks, or personal score monitoring. A soft pull has zero impact on your credit score and is invisible to other lenders viewing your file. When you check preliminary options on modern loan marketplaces, providers typically initiate a soft check.
- Hard Credit Inquiry: Occurs when you formally submit an application for an offer you wish to accept. A hard inquiry can temporarily shave 2 to 5 points off your credit score and remains on your credit report for up to 24 months (though its score impact fades within a few months).
2. The 5 Pillars of Your Credit Score
To understand how an installment loan interacts with your credit profile over time, consider the breakdown of the standard FICO scoring model:
The remaining 25% consists of Length of Credit History (15%) and New Credit Inquiries (10%).
3. Positive Impacts of Installment Loans
When managed responsibly, an installment loan can positively influence multiple areas of your credit profile:
- Establishes Consistent Payment History: Every scheduled monthly payment reported to Equifax, Experian, or TransUnion builds a positive track record. Over a 12 to 36 month term, dozens of on-time marks prove reliable borrowing behavior.
- Lowers Revolving Credit Utilization: If you use an installment loan to consolidate credit card debt, your revolving credit utilization ratio plummets from 80-90% toward near 0%, which can quickly raise your credit score.
- Diversifies Credit Mix: Lenders prefer seeing that you can handle both revolving credit (credit cards) and fixed installment credit (personal loans or auto loans).
4. Potential Risks to Your Credit Profile
While the upside is tangible, there are real risks if a loan is mismanaged:
- Late or Missed Payments: Payments 30 days past due are reported to bureaus and can drop a credit score by 50 to 100 points, staying on your credit history for up to 7 years.
- Excessive Debt-to-Income (DTI): Adding a monthly installment obligation increases your total debt service. If you plan to apply for a mortgage in the immediate future, an added monthly payment could impact debt-to-income qualification.
- Running Up Card Balances Again: If you consolidate credit card debt but continue charging on those same cards, you double your debt burden.
5. The "Rate Shopping" Window Rule
Credit scoring models acknowledge that smart consumers shop around for the best rates. Under FICO rules, multiple hard inquiries for the same type of loan (such as mortgages, auto loans, and certain student or personal credit inquiries) that occur within a condensed window (typically 14 to 45 days) are treated as a single inquiry.
6. Best Practices to Protect Your Score
2. Keep Paid-Off Cards Open: If you consolidate credit card debt, keep the old zero-balance accounts active to preserve your account age and overall credit limit.
3. Check Pre-Qualification First: Always seek lenders that offer soft-inquiry pre-qualification before committing to a hard credit check.
Check Eligibility with Confidence
Review loan options through our secure connection service. Evaluate potential rates and payment terms today.